Insured for the Mortgage, Not the Rebuild? Five Checks Before the Coinsurance Clause Bites
The averaging clause reduces a paid claim by the ratio of what you carried to what you should have carried, and the first weeks of a policy are when that ratio is still fixable.
Pinned by Josephine Lachance5 min read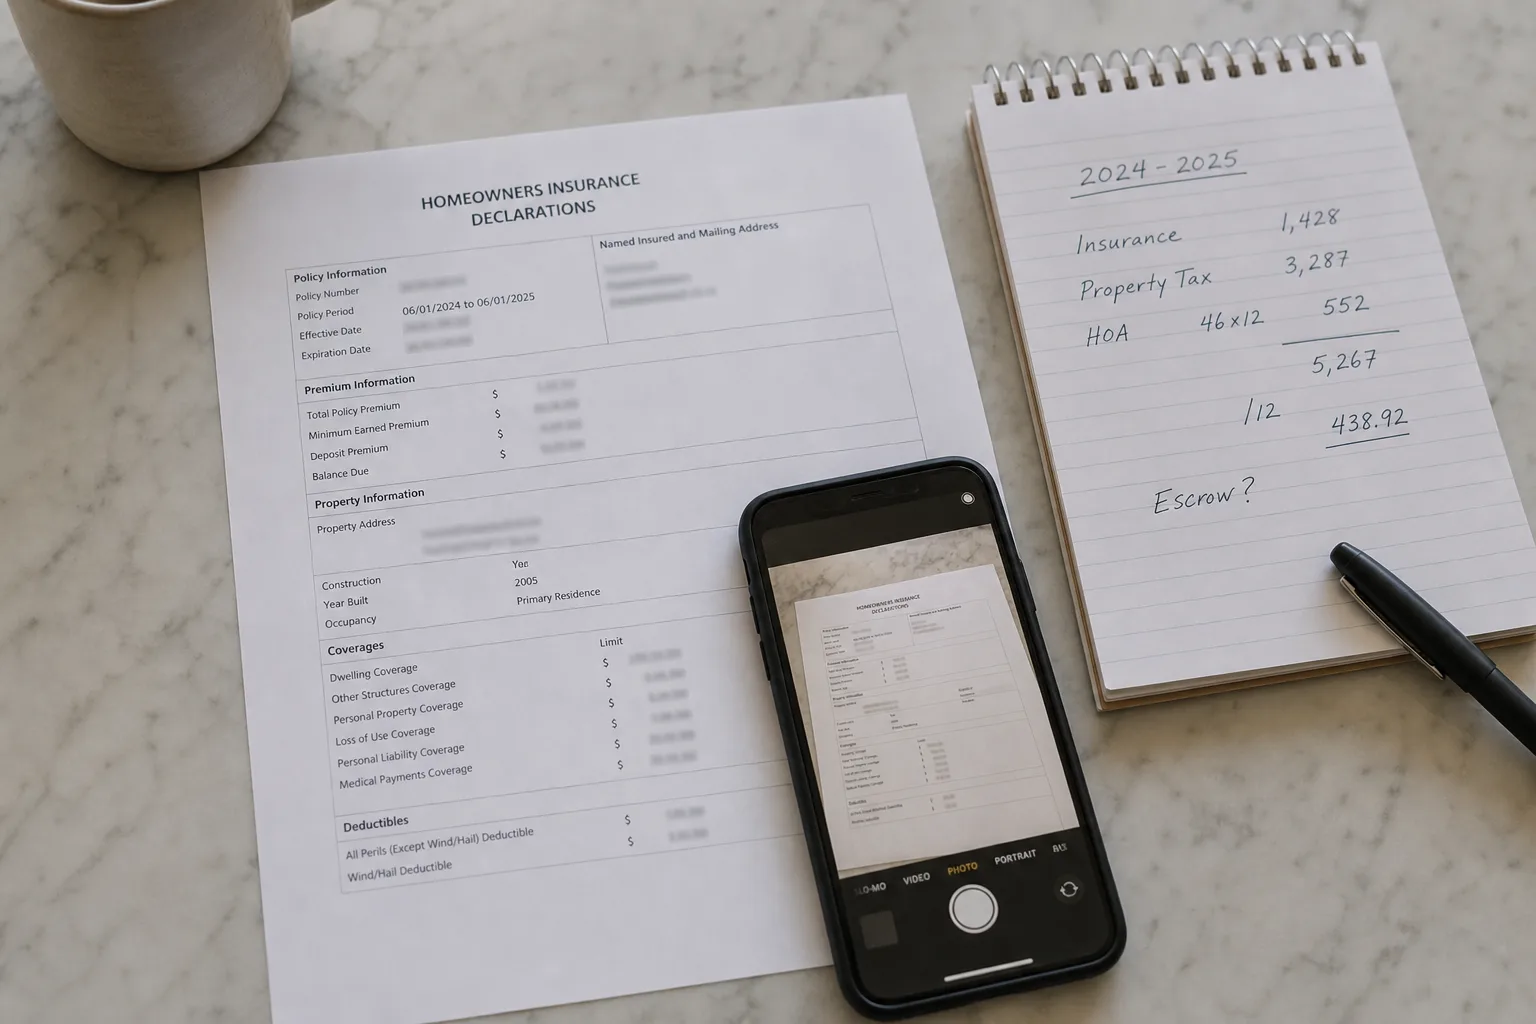 A homeowner's insurance declarations page laid flat on a kitchen table beside a smartphone photographing it, with a handwritten notepad showing figures along...
The condition that quietly reduces a paid claim is rarely on the page the agent walked you through. It sits in the property conditions, under a heading like coinsurance or insurance to value, and it does not announce itself at renewal because nothing about it changes year to year except the gap it is measuring. That gap is between the limit you carry and the limit the policy says you should carry, and it widens on its own, through construction cost inflation, a finished basement, a new roof, an addition nobody reported. The first weeks of a policy are when the gap is cheapest to close.
One. The percentage and the valuation basis, read off the declarations page
Open the declarations page and find three things: the Coverage A limit, the coinsurance percentage if one is stated, and whether the loss settlement basis is replacement cost or actual cash value. Photograph that page, in full, the day it arrives, and keep the photograph with the policy number in the file name. Coinsurance percentages are commonly set at eighty, ninety or one hundred percent of the insurable value, and the number matters more than most buyers expect, because it is the denominator in every reduction that follows. If the page says nothing about coinsurance, write to the agent and ask, in an email rather than a call, whether the condition applies and at what percentage. Get the answer in text you can retrieve.
Two. The arithmetic the clause performs, before it performs it
The averaging formula is mechanical and worth running once while nothing is on fire. The insurer takes the amount of insurance carried, divides it by the amount required (the coinsurance percentage multiplied by the replacement cost of the structure), and applies that fraction to the loss, then subtracts the deductible. Carry three quarters of what the condition requires and the fraction is three quarters, which is survivable on a small loss and painful on a large one. The clause bites hardest on partial losses, the kitchen fire, the burst supply line upstairs, precisely the claims that make up most of what households actually file. Run the fraction with your own limit on paper and keep the sheet.
Three. Rebuild cost, not market value, and who is willing to put a number on it
The number the clause tests against is the cost to rebuild the structure with like materials at current labor rates, which has almost nothing to do with what the house would sell for or what the lender required at closing. Land is not in it. Neither is the market's opinion of the school district. Ask your agent for the replacement cost estimate the carrier used, in writing, with the date it was generated and the square footage, finish grades and construction type it assumed, then read those assumptions against the house you actually own. If the estimate says builder-grade cabinets and the kitchen has custom ones, that discrepancy is yours to correct now, not to argue about later. A contractor's dated estimate for a comparable rebuild is a useful second document to hold.
Four. Inflation guard, endorsements, and the reporting deadlines attached to them
Most residential policies carry some automatic increase in the dwelling limit at each renewal, and many offer extended replacement cost, which pays a stated percentage above the limit, or guaranteed replacement cost, which pays the rebuild regardless of the limit. Those endorsements are the practical answer to averaging, and they come with conditions. The common one is a duty to report improvements that increase the value of the dwelling, often within a set window of days after completion, and a failure to report can suspend the very protection you bought. Note the window in the calendar the day the endorsement is added. When you finish a renovation, send the description, the cost and the completion date to the agent by email and file the reply.
Five. The record that establishes what you told the insurer, and when
Under-insurance disputes are almost always disputes about information: what the carrier knew about the property, what you disclosed, whether the limit reflected a request you made or a default nobody revisited. That argument is decided by documents, so build the documents while the policy is new and the facts are dull. Keep the application or the agent's worksheet, the declarations page for each year, every email in which you asked for a limit increase or reported work, and a dated photographic walkthrough of each room, the exterior elevations, the mechanical systems and the roof. Photograph serial number plates on the furnace and the water heater. A contents inventory with purchase dates does the same job on the personal property side.
What the rules already give you, and where to press
Property insurance is regulated at the state level, by a department of insurance that reviews policy forms, licenses producers and takes consumer complaints, which means the coinsurance language in your policy was filed and approved rather than improvised for you. That has two practical consequences. The condition will read closely the same across carriers in your state, so the version in your policy is worth learning once. And the department will accept a complaint if a claim is reduced under a condition you can show was never explained, was applied to the wrong valuation basis, or was calculated against an estimate the carrier itself produced and never updated. On the flood side, the National Flood Insurance Program is administered by the Federal Emergency Management Agency, which sets the coverage terms and the coinsurance treatment nationally rather than leaving them to individual carriers, so the same reading exercise applies to a separate document with its own limits.
The half hour that closes the gap
Set aside one sitting and do it in order. Photograph the declarations page. Write the coinsurance percentage, the Coverage A limit and the required amount at that percentage on a single sheet, with the date. Email the agent three questions: what replacement cost estimate supports this limit, what endorsements are on the policy that modify the coinsurance condition, and what the reporting deadline is for improvements. Then walk the house with a camera and finish the visual record in an afternoon. The whole file fits in one folder, cloud-stored and shared with a second household member, and it converts a future argument about memory into a matter of retrieval.
A limit that was right at closing tends to be wrong three years on, not because anyone made a mistake but because construction costs move and houses change. The correction is a phone call and a premium adjustment, both small, and the window for making it is any ordinary week in which nothing has happened. Write down what you find, send what you learn in an email that leaves a copy behind, and the coinsurance condition becomes a calculation you have already run rather than one performed on you.
Posted under Money & Finance