A Collection Letter, a Debt That Isn't Yours, and the Thirty Days That Decide Everything
A collection notice for an account you do not recognize is usually settled in writing, but a few versions of it genuinely need counsel, and the difference is visible early.
Pinned by Miriam Goldfarb5 min read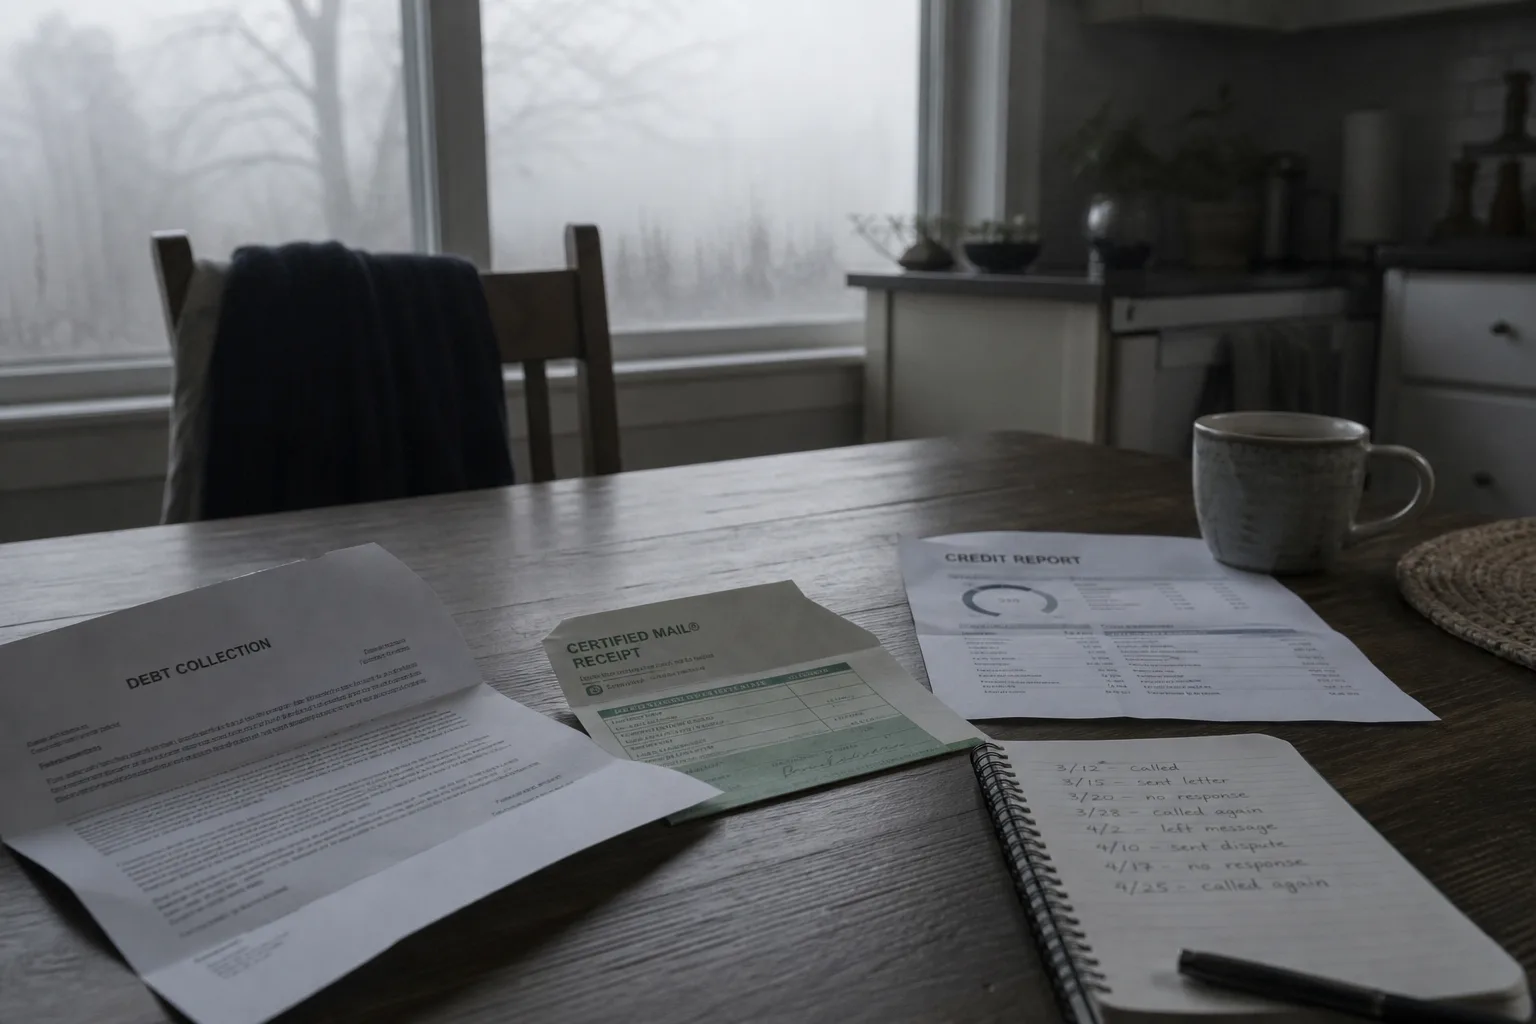 A kitchen table with an opened debt collection letter, a certified mail receipt with a green return card, a printed credit report, and a spiral notebook with...
Most of what a debt collector may and may not do sits in federal statute, and the strongest protection you have starts running the day the first written notice reaches you. That matters because the letter itself is designed to look urgent and final, with a balance, an account number you have never seen, and the name of a company that is not the one you originally borrowed from. Very little about that letter obliges you to move fast in the way it implies. What does oblige you to move fast is the window in which a written dispute carries legal weight, and that window is short.
One. The written dispute, sent inside the window, and sent so you can prove it
Under the federal debt collection rules, a collector's first communication has to tell you that you may dispute the debt in writing within thirty days, and that a timely dispute obliges the collector to stop collection activity until it verifies the account and mails you the verification. This is the single most useful thing a consumer can do alone, at the cost of postage. Send it certified with return receipt, keep the green card, and keep a copy of what you sent. The Consumer Financial Protection Bureau is responsible for the rules that govern third-party collectors, and the dispute process it administers works without a lawyer standing behind it.
Ask for specifics rather than filing a general objection. The name of the original creditor, the date of the last payment, the amount broken into principal, interest and fees, and the chain of ownership if the account has been sold more than once. Collectors who bought a portfolio in bulk often cannot produce those documents quickly, and a dispute that names them is harder to answer with a form letter. Many accounts simply stop being pursued at this stage, quietly, without anyone telling you why.
Two. Whether it is your debt at all, which is a records problem before it is a legal one
A large share of these letters are not fraud and not error in the dramatic sense. They are a common surname, a junior and a senior at the same address, a reassigned phone number, an old account a joint owner closed years ago, or a medical balance that an insurer was supposed to pay and did not. Pull your credit reports from all three bureaus and see whether the account appears, how it is reported, and what dates are attached to it. The dates matter more than the balance, because they tell you how old the underlying account is.
If the account is on your report and is not yours, dispute it with the bureau as well as the collector, since those are separate processes with separate obligations. Keep the two tracks in one folder with a simple date log at the front. What you are building is not an argument yet. It is the record that makes an argument cheap to construct later, if one becomes necessary, and that makes an attorney's first hour productive instead of exploratory.
Three. The moment the paperwork stops being a letter and becomes a court document
There is a clean line here and it is worth recognizing on sight. A dunning letter, a phone call, a settlement offer at forty cents on the dollar, a notice that the account has been placed with a new agency: all of these are collection activity, and you can handle all of them in writing. A summons and complaint is different. It has a case number, a court name, and a deadline to file a written answer, usually counted in days from the date you were served, and missing it produces a default judgment that is far harder and more expensive to undo than it would have been to contest.
Garnishment notices, a bank levy, and any judgment you learn about after the fact belong in the same category. So does any letter that threatens criminal consequences, or that arrives about a debt you already discharged in bankruptcy. In each of those situations the question is no longer whether the debt is yours. It is procedural, time-bound, and answered in a courtroom, and that is precisely the work attorneys are licensed to do.
Four. Fee shifting, which changes who actually pays for the lawyer
Consumer protection statutes in this area generally allow a prevailing consumer to recover attorney's fees from the violating collector. The practical effect is that a substantial number of consumer law attorneys take these cases on contingency, review the file for free, and get paid by the other side rather than by you. Someone who assumes a lawyer is unaffordable often never makes the call that would have cost nothing. Ask directly in the first conversation who pays if you win, who pays if you lose, and whether court costs and filing fees are treated separately from fees.
Bring the file when you ask. The envelopes with postmarks, a call log with dates and times, any voicemail recordings, the certified mail receipt, and the credit reports. Violations in this area are documented by dates and repetitions, and the attorney is assessing in the first ten minutes whether your records can carry that weight.
Five. Reading the reviews, and separating a pattern from a grudge
Online ratings for attorneys measure something real, but it is narrower than the star count suggests. What reviewers reliably report is contact: whether calls were returned, whether they understood what was happening, whether the bill matched the estimate. What they report poorly is legal skill, because a client who lost rarely distinguishes a weak case from weak representation. Read the one and two star reviews first and sort them by subject. One furious review about an outcome is a grudge. Six reviews across three years describing unreturned calls is a pattern, and it is the pattern that will affect you.
Recency carries more information than volume, since staff turn over and a practice that was responsive in 2019 may not be now. Then step outside the review sites entirely and check the attorney's standing and any public discipline history with your state bar, which licenses and regulates practice in your state. That record covers the things reviewers never see, and it is the check that makes the rest of the reading worth doing.
The useful habit is to treat the first letter as the start of a file rather than a demand for an answer. Date everything, dispute in writing within the window, and keep the envelopes. If the matter ever reaches a courthouse, you will hand someone a folder instead of a memory, and the hour you buy will go toward strategy.
Posted under Law & Legal